

Mortgage Rate Trends & Housing Affordability 2026 Infographic
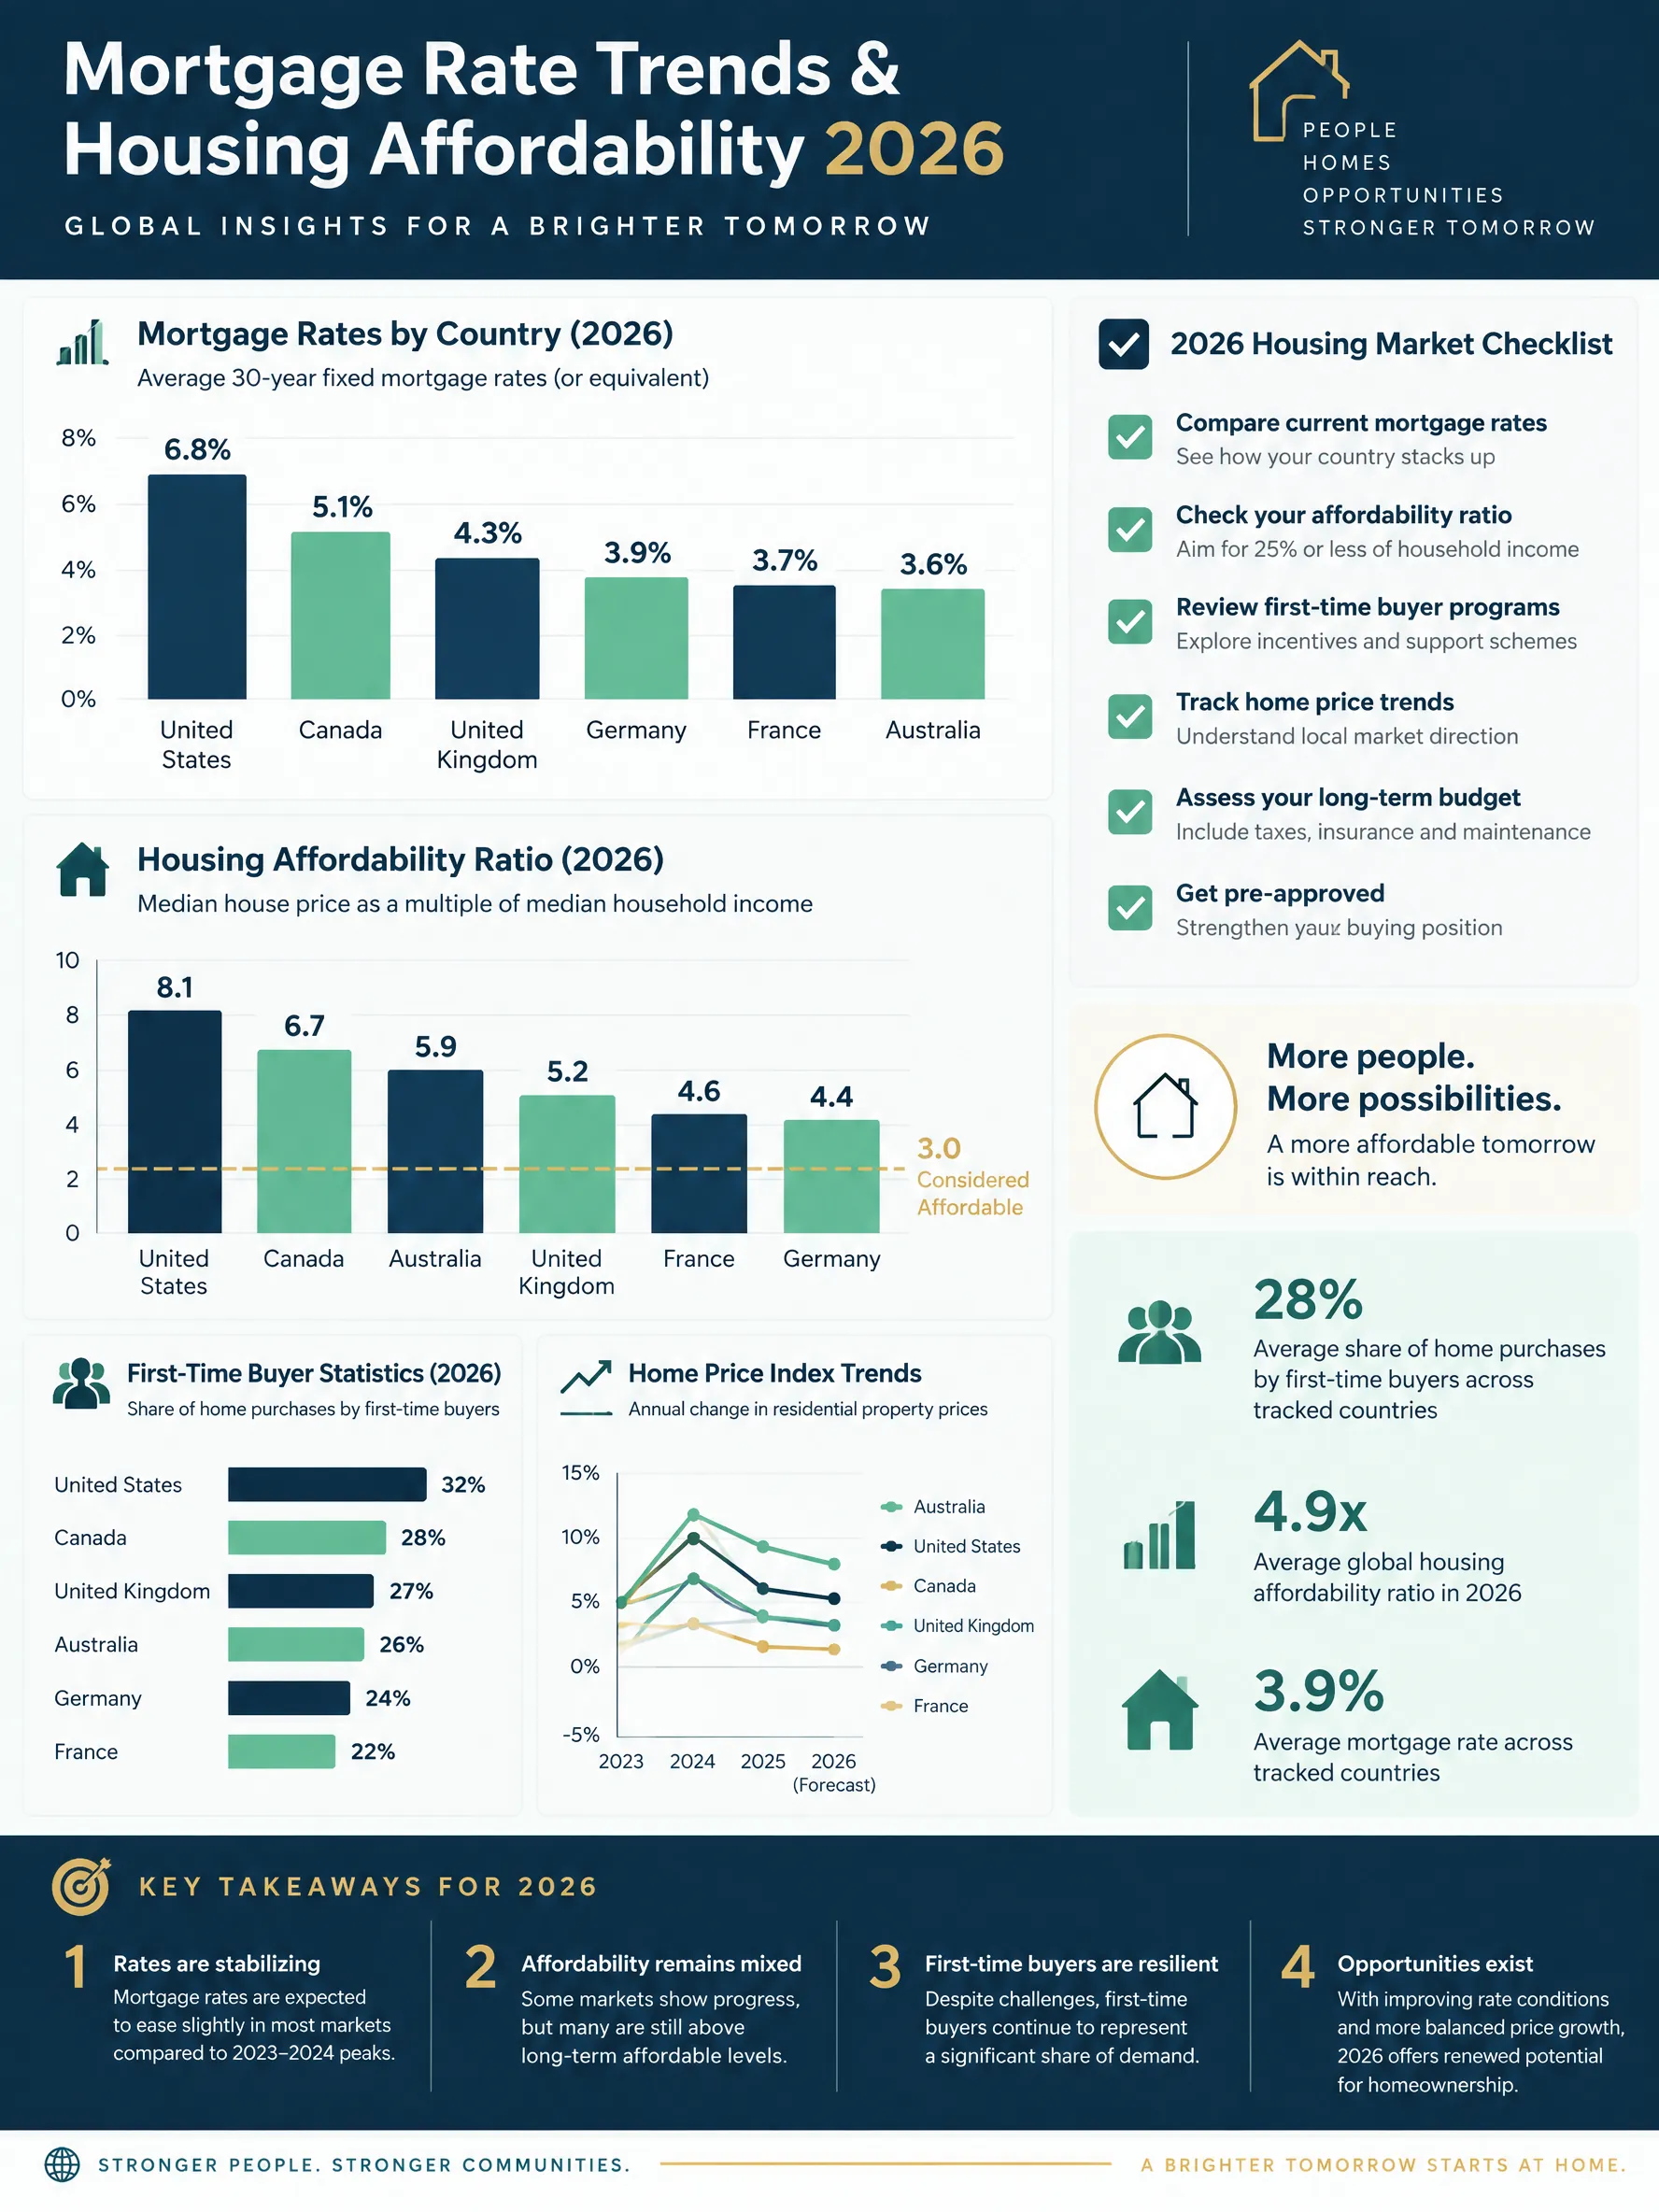
Mortgage rate data by country, housing affordability ratios, first-time buyer statistics, home price index trends, and buyer checklist for 2026.
Published
Generate a custom version of this infographic
Customize with your own data, style, and branding
Generate This InfographicAction Items
Essential Mortgage Rate Trends & Housing Affordability 2026
Housing affordability has become one of the defining economic challenges of the 2020s, with home prices outpacing income growth in nearly every major market worldwide. In 2026, the global housing market sits at a complex inflection point: mortgage rates have begun moderating from their 2023-2024 peaks, but prices remain elevated, creating both opportunities and challenges for buyers. This checklist guide covers essential data points, market conditions, and actionable steps for prospective homebuyers.
Mortgage rates vary significantly across economies. In the United States, the 30-year fixed rate averaged 5.8% in mid-2026, down from a peak of 7.8% in late 2023 but well above the 3.0% pandemic lows. The UK base rate-linked mortgage rates sit at 4.2-5.5%. The Eurozone average is 3.8%, though rates range from 2.9% in France to 4.5% in Italy. Australia's variable rates hover at 5.6%. Japan remains an outlier at 1.2-1.8% as the Bank of Japan maintains its gradualist approach to policy normalization. Canada's rates have declined to 4.5% from the 2023 peak of 6.5%. These rate differences reflect divergent central bank policies, inflation trajectories, and housing market structures.
Housing affordability ratios paint a sobering picture. The median home price-to-income ratio in major cities: Hong Kong (18.8x), Sydney (13.3x), Vancouver (12.0x), London (11.4x), Los Angeles (10.8x), San Francisco (10.2x), Auckland (9.5x), Toronto (9.0x), Singapore (8.5x), and New York (7.8x). The generally accepted affordable threshold is 3.0-5.0x annual income. In the US nationally, the ratio stands at 5.4x — meaning the median household must spend 5.4 years of gross income to purchase the median home. First-time buyers face steeper challenges: the average age of first-time homebuyers in the US rose to 36 (from 29 in 2000), in the UK to 34, and in Australia to 37.
The buyer readiness checklist for 2026 includes essential financial and market preparedness steps. Financial foundation: credit score above 720 for best rates (US), 6-12 months of expenses in emergency fund maintained separately from down payment savings, debt-to-income ratio below 36% (43% maximum for qualified mortgage). Down payment benchmarks: 20% avoids PMI in the US ($72,000 on median-priced $360,000 home), though programs exist for 3-5% down for first-time buyers. In the UK, 5-10% deposits are standard; Australia offers the First Home Guarantee with 5% deposit. Pre-approval process: gather 2 years of tax returns, 3 months of bank statements, employment verification, and debt documentation before applying.
Market timing considerations for 2026 include several factors favoring action. Rate forecast: most economists project US 30-year rates declining to 5.2-5.5% by year-end as the Fed continues its easing cycle — each 0.5% rate drop saves roughly $85/month on a $350K mortgage. Inventory is recovering: existing home listings increased 22% year-over-year as rate-locked homeowners begin selling, reducing competition. New construction starts reached 1.5 million annualized units, the highest since 2006. However, home prices remain elevated: the S&P Case-Shiller Index shows 3.2% annual appreciation nationally, with Sun Belt markets cooling while Northeast and Midwest see modest gains. The 'lock-in effect' is fading as homeowners who refinanced at 3% pandemic rates accept the need to move for life changes, gradually normalizing inventory levels.
Frequently Asked Questions
Is 2026 a good time to buy a home?
Should I wait for mortgage rates to drop further?
How much do I need for a down payment in 2026?
Sources
- Freddie Mac, Primary Mortgage Market Survey, 2026
- Demographia, International Housing Affordability Report, 2026
- National Association of Realtors (NAR), Home Buyers and Sellers Generational Trends, 2026
- Realtor.com, Monthly Housing Market Trends, 2026
- S&P Global, Case-Shiller Home Price Index, 2026
Source links go to each publisher's official website.
Embed This Infographic
Copy the code below to share this infographic on your website
<a href="https://www.makeinfographics.ai/infographic/mortgage-rate-trends-housing-affordability-2026" target="_blank" rel="noopener">
  <img src="https://www.makeinfographics.ai/images/infographics/mortgage-rate-trends.webp"
       alt="Mortgage Rate Trends & Housing Affordability 2026 — Mortgage rate data by country, housing affordability ratios, first-time buyer statistics, home price"
       width="960" height="1280" loading="lazy"
       style="max-width:100%;height:auto;" />
</a>
<p>Source: <a href="https://www.makeinfographics.ai">MakeInfographics.ai</a> — Free AI Infographic Generator</p>
Create Your Own Mortgage Rate Trends & Housing Affordability 2026 Infographic
Customize this topic with your own data, style, and branding
Create Custom Version — FreeRelated Infographics
All Real Estate infographics →Home Buying Process: From Pre-Approval to Closing
A step-by-step visual guide to buying a home — from mortgage pre-approval through house hunting, inspections, and closing day. Includes timelines, costs, and expert tips.
Global Real Estate Investment Trends 2026
Data-driven overview of worldwide real estate investment volumes, cap rates, REIT performance, cross-border capital flows, and emerging market opportunities for investors.
Smart Home Technology Adoption 2026
Comprehensive guide to smart home adoption rates, device categories, market size, IoT growth projections, and consumer spending patterns across global markets.
Commercial Real Estate Trends 2026
Data-driven overview of the 2026 commercial real estate market covering office vacancy rates, industrial demand, retail recovery, and investment flows across major metropolitan areas.