
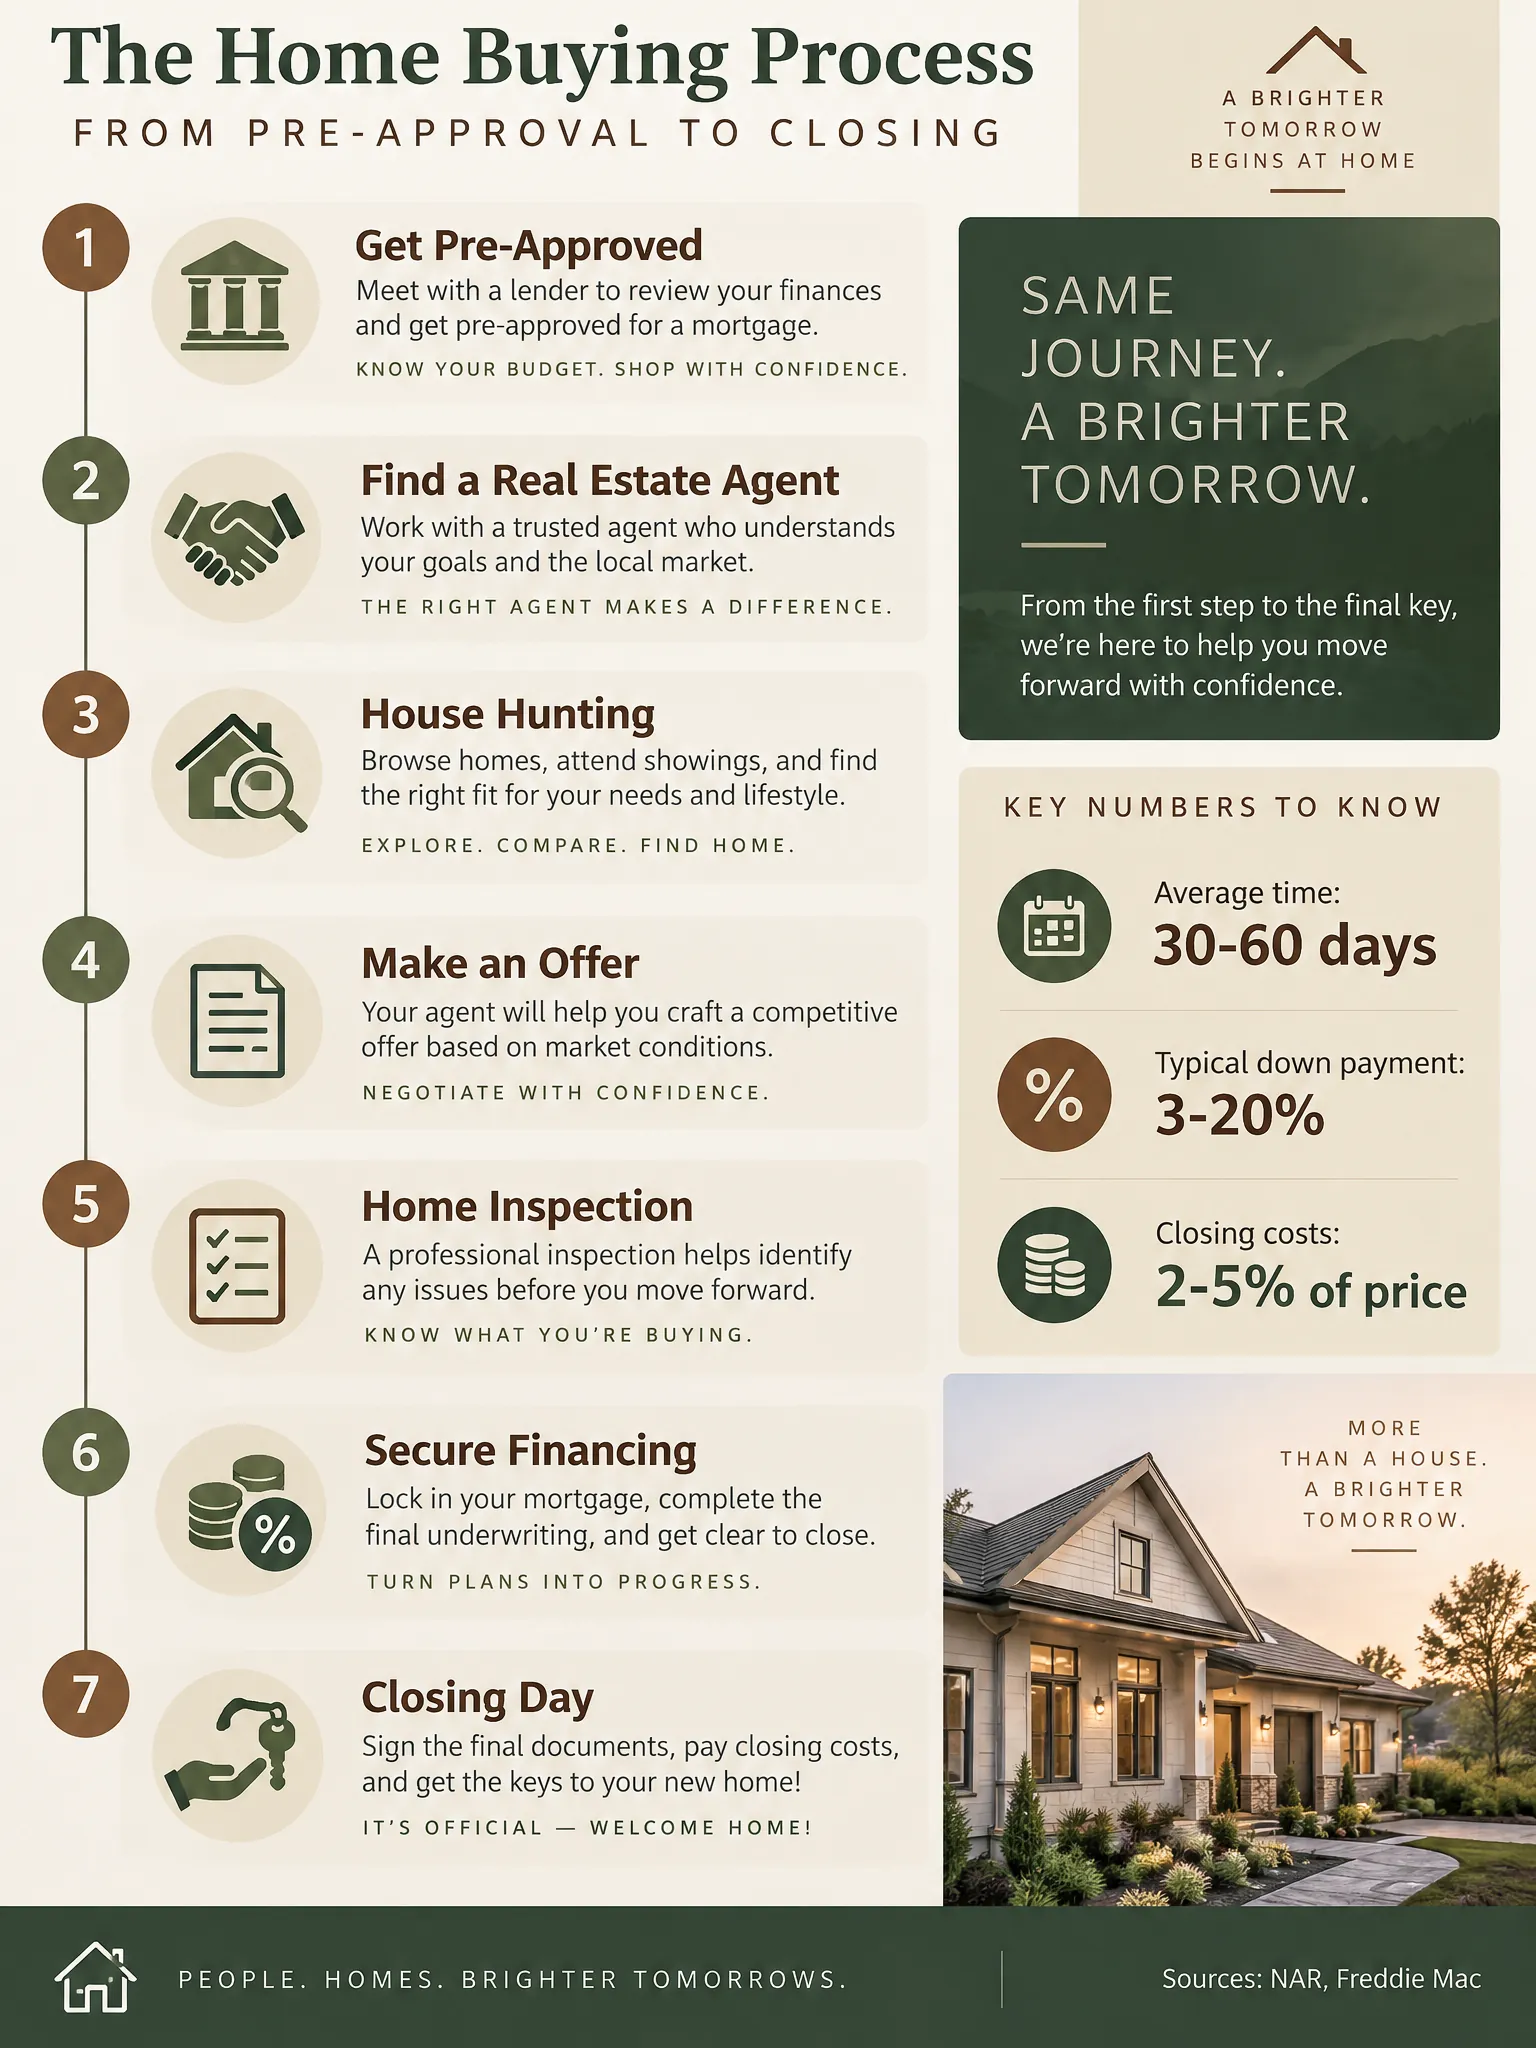
Home Buying Process: From Pre-Approval to Closing Infographic
From pre-approval to closing: 30–60 days after offer, 86% finance purchases, and average closing costs hit about $6,900 in 2025.
Published
Generate a custom version of this infographic
Customize with your own data, style, and branding
Generate This InfographicProcess Steps
How Home Buying Process: From Pre-Approval to Closing
Purchasing a home is the largest financial transaction most people will ever make, yet the process remains opaque for many first-time buyers. Understanding each stage — from initial financial preparation through closing — reduces stress, prevents costly mistakes, and puts buyers in a stronger negotiating position. The typical home purchase takes 30 to 60 days from accepted offer to closing, though the total journey from first consideration to keys in hand often spans four to six months.
The process begins with financial preparation. Before browsing listings, buyers should review their credit score (a score above 740 secures the best rates), calculate their debt-to-income ratio, and get pre-approved for a mortgage. Pre-approval differs from pre-qualification: it involves a hard credit pull, income verification, and produces a letter stating the exact loan amount a lender will commit to. According to the National Association of Realtors, 86 percent of recent buyers financed their purchase, with a median down payment of 15 percent for all buyers and 8 percent for first-time buyers.
Finding the right real estate agent is the next critical step. A buyer's agent represents your interests exclusively, helps navigate local market conditions, and typically costs the buyer nothing — their commission is paid by the seller. The best agents bring local market knowledge, negotiation expertise, and access to listings before they hit public platforms. NAR data shows that 89 percent of buyers purchased their home through a real estate agent in 2025.
House hunting itself requires balancing needs versus wants. Most buyers tour 7 to 10 homes before making an offer. Key evaluation criteria include location, school districts, commute times, structural condition, and future resale value. In competitive markets, buyers may need to act quickly — the median time a home spent on market in 2025 was just 24 days.
Once you find the right property, your agent helps craft a competitive offer. The offer includes purchase price, earnest money deposit (typically 1 to 3 percent of the price), contingencies for inspection and financing, and a proposed closing date. In a balanced market, expect some negotiation. After acceptance, the clock starts on the due diligence period.
The home inspection is arguably the most important contingency. A licensed inspector evaluates the property's structure, electrical, plumbing, HVAC, roof, and foundation. Inspections typically cost $300 to $500 and take two to three hours. If significant issues are found, buyers can negotiate repairs, request a price reduction, or exercise their right to walk away.
Closing day involves signing a substantial stack of documents, transferring funds, and officially taking ownership. Closing costs — which include lender fees, title insurance, appraisal fees, and prepaid items — typically range from 2 to 5 percent of the purchase price. The average closing cost in the United States was approximately $6,900 in 2025, excluding transfer taxes. After the final walkthrough and document signing, you receive the keys to your new home.
Market conditions in 2025 reshaped how long each process step takes. With median days on market near twenty-four days, pre-approval and agent selection are no longer leisurely preludes—they determine whether a buyer can submit a credible offer quickly. NAR figures show most purchasers still finance, with a median 15 percent down overall and 8 percent for first-timers, so loan type and mortgage insurance rules belong in the budget conversation before touring begins. Competitive markets reward buyers who understand contingency trade-offs and earnest money norms of 1 to 3 percent.
Due diligence extends beyond the standard inspection. Appraisals protect lenders but can gap below offer price in fast-appreciating neighborhoods, forcing renegotiation or additional cash. Title review and homeowner insurance binding happen in parallel with underwriting; delays often trace to document requests rather than the closing appointment itself. Closing costs averaging about $6,900 nationally, typically 2 to 5 percent of price, should be reserved alongside down payment funds so cash-to-close surprises do not derail the transaction.
First-time buyers commonly underestimate total ownership costs—maintenance, property taxes, and HOA fees sit outside the mortgage payment. Skipping pre-approval, waiving inspection without alternatives, or choosing an agent without local transaction volume are frequent errors. Conversely, buyers who tour seven to ten homes with clear must-have lists, keep inspection findings negotiable, and compare lender fees line by line tend to finish the thirty-to-sixty-day contract period with fewer last-minute crises.
Through the rest of the decade, digital closings and remote notarization should shorten administrative friction, but local supply and rate environments will still dominate timing. Treat the journey as four to six months from decision to keys: financial prep, search with professional representation, contracted diligence, then settlement day when documents, wire transfers, and final walkthrough converge.
Frequently Asked Questions
How long does it take to buy a house from start to finish?
How much do I need for a down payment on a house?
What are closing costs and how much should I expect to pay?
Do I need a real estate agent to buy a house?
Sources
- National Association of Realtors (NAR), Profile of Home Buyers and Sellers, 2025
- Freddie Mac, My Home Buying Guide, 2025
- CoreLogic ClosingCorp, Closing Cost Report, 2025
- American Society of Home Inspectors (ASHI), 2025
Source links go to each publisher's official website.
Embed This Infographic
Copy the code below to share this infographic on your website
<a href="https://www.makeinfographics.ai/infographic/home-buying-process-guide" target="_blank" rel="noopener">
  <img src="https://pic-cdn.chibistyle.app/infographics/infographics/home-buying-process.webp"
       alt="Home Buying Process: From Pre-Approval to Closing — From pre-approval to closing: 30–60 days after offer, 86% finance purchases, and average closing cos"
       width="960" height="1280" loading="lazy"
       style="max-width:100%;height:auto;" />
</a>
<p>Source: <a href="https://www.makeinfographics.ai">MakeInfographics.ai</a> — Free AI Infographic Generator</p>
Create Your Own Home Buying Process: From Pre-Approval to Closing Infographic
Customize this topic with your own data, style, and branding
Create Custom Version — FreeMake Something for Your Own Life
Free printable planners, blank or filled in by AI from your details.
Related Infographics
All Real Estate infographics →First-Time Home Buyer Guide 2026
Median US home $425K, 5.8% mortgage rates, 8% typical down payment, 2,400+ assistance programs—2026 first-time buyer facts.
Property Appraisal Process & Home Valuation Guide 2026
About 5.2M US home appraisals yearly: USPAP inspection steps, comp adjustments, AVM waivers, desktop share, and how to handle low values.
Mortgage Rate Trends & Housing Affordability 2026
Mortgage rate data by country, housing affordability ratios, first-time buyer statistics, home price index trends, and buyer checklist for 2026.
Luxury Real Estate Market Trends 2026
Monaco leads at $5,490/sq ft; Dubai +12% YoY luxury growth, UHNWI buyers, yields, and global prime market comparisons for 2026.