
Personal Finance Budget Planning Checklist Infographic
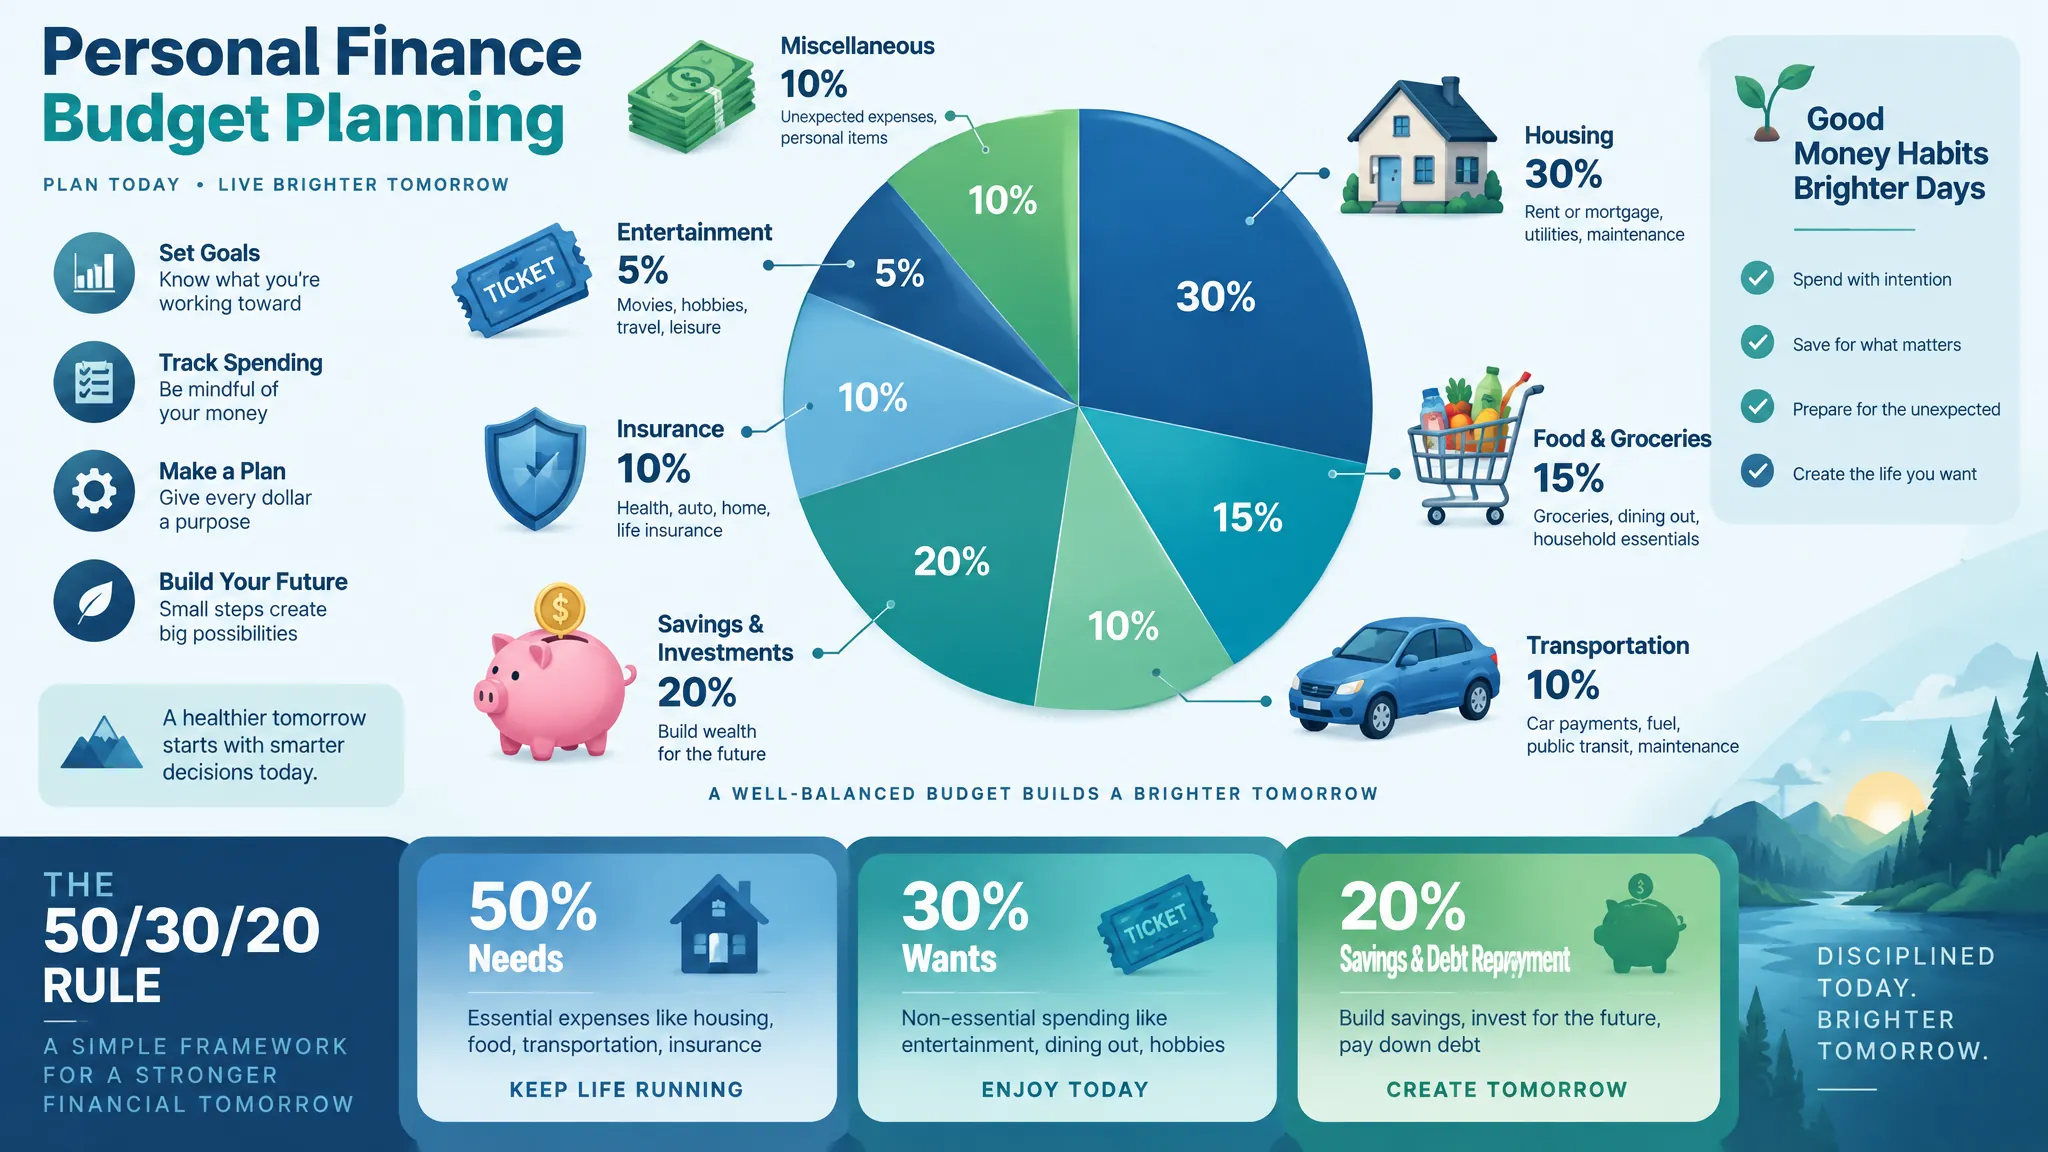
2026 budget checklist: 53% of U.S. adults budget, households spend ~$78.5K on ~$104K income, and 50/30/20 splits needs, wants, and savings.
Published
Generate a custom version of this infographic
Customize with your own data, style, and branding
Generate This InfographicAction Items
Essential Personal Finance Budget Planning Checklist
Building a personal budget is the single most impactful step toward financial stability, yet only 53 percent of American adults set a budget for 2026 — up from 46 percent the previous year, according to YouGov research. With the average U.S. household spending 78,535 dollars annually against a pretax income of 104,207 dollars, understanding where every dollar goes is critical to avoiding the spending trap that leaves 37 percent of adults unable to cover a 400-dollar emergency with cash or its equivalent.
The most widely recommended framework is the 50/30/20 rule: allocate 50 percent of after-tax income to needs such as housing, groceries, utilities, insurance, and minimum debt payments; 30 percent to wants including dining out, entertainment, subscriptions, and travel; and 20 percent to savings and extra debt repayment. While the exact percentages can be adjusted to individual circumstances, this structure provides a clear starting point that prevents both overspending and excessive frugality.
Effective budgeting begins with a full expense audit. Track every transaction for at least 30 days to reveal hidden spending patterns — the daily coffee run, unused streaming subscriptions, or impulse online purchases that quietly erode your financial margin. Federal Reserve data shows that 41 percent of adults always or often had money left at month-end in 2025, meaning the majority either broke even or overspent. Identifying and eliminating just two or three unnecessary recurring expenses can redirect hundreds of dollars per month toward high-impact financial goals.
An emergency fund is the cornerstone of financial resilience. Financial advisors recommend saving three to six months of essential expenses in a high-yield savings account. The Financial Health Network reports that only 31 percent of U.S. households were considered financially healthy in 2025, largely because too few families maintain adequate liquid reserves. Start with a 1,000-dollar starter fund, then build systematically by automating transfers on each payday. Once your emergency fund is established, redirect surplus savings toward retirement accounts, investment portfolios, or specific goals like a home down payment.
Debt management deserves equal attention in any budget plan. The avalanche method — paying minimums on all debts while throwing extra money at the highest-interest balance — minimizes total interest paid. The snowball method — targeting the smallest balance first — provides faster psychological wins. Either approach is effective; the key is consistency. With 29 percent of households reporting unmanageable debt levels in 2025, a structured payoff strategy can transform financial stress into measurable progress within months.
In expensive metros, couples may exceed that ratio yet stay solvent only if transportation, debt service, and discretionary lines stay disciplined within a fifty-thirty-twenty style plan.
Inflation and saving rate trends add urgency in 2026. A thirty-day transaction audit reveals leaks—unused subscriptions, delivery fees, and buy-now-pay-later balances—that matter because only about 41 percent of adults consistently end the month with surplus cash.
Insurance and benefits belong in the needs column, not as afterthoughts. Health premiums, auto coverage, and renters or homeowners policies stabilize catastrophic risk so emergency funds are not wiped out by a single event. Meanwhile, capturing the full employer 401(k) match before aggressive debt payoff preserves an immediate return that beats most interest spreads except high-rate credit cards.
Review cadence turns a static checklist into a living plan. Quarterly reconciliation of categories, annual rebasing of the fifty-thirty-twenty splits after raises or life changes, and automated transfers on payday reduce reliance on willpower. Households that spent less than income over the past year in national surveys share that structural automation more than one-off austerity.
Automation protects the plan when attention lapses. Scheduled transfers to savings and retirement accounts on payday, bill reminders, and a single weekly check-in make it easier to follow the budget than relying on willpower alone.
Frequently Asked Questions
What is the 50/30/20 budgeting rule?
How much should I have in an emergency fund?
What percentage of income should go to housing?
How do I start budgeting if I have irregular income?
What is better for paying off debt — avalanche or snowball method?
Sources
- Federal Reserve, Survey of Household Economics and Decisionmaking (SHED), 2025
- Bureau of Labor Statistics, Consumer Expenditure Survey, 2024
- Financial Health Network, Financial Health Pulse 2025 U.S. Trends Report
- YouGov, U.S. Consumer Spending and Budgeting Trends, 2026
- Bureau of Economic Analysis, Personal Saving Rate, 2026
Source links go to each publisher's official website.
Embed This Infographic
Copy the code below to share this infographic on your website
<a href="https://www.makeinfographics.ai/infographic/personal-finance-budget-planning" target="_blank" rel="noopener">
  <img src="https://pic-cdn.chibistyle.app/infographics/infographics/budget-planning.webp"
       alt="Personal Finance Budget Planning Checklist — 2026 budget checklist: 53% of U.S. adults budget, households spend ~$78.5K on ~$104K income, and 50/"
       width="960" height="540" loading="lazy"
       style="max-width:100%;height:auto;" />
</a>
<p>Source: <a href="https://www.makeinfographics.ai">MakeInfographics.ai</a> — Free AI Infographic Generator</p>
Create Your Own Personal Finance Budget Planning Checklist Infographic
Customize this topic with your own data, style, and branding
Create Custom Version — FreeMake Something for Your Own Life
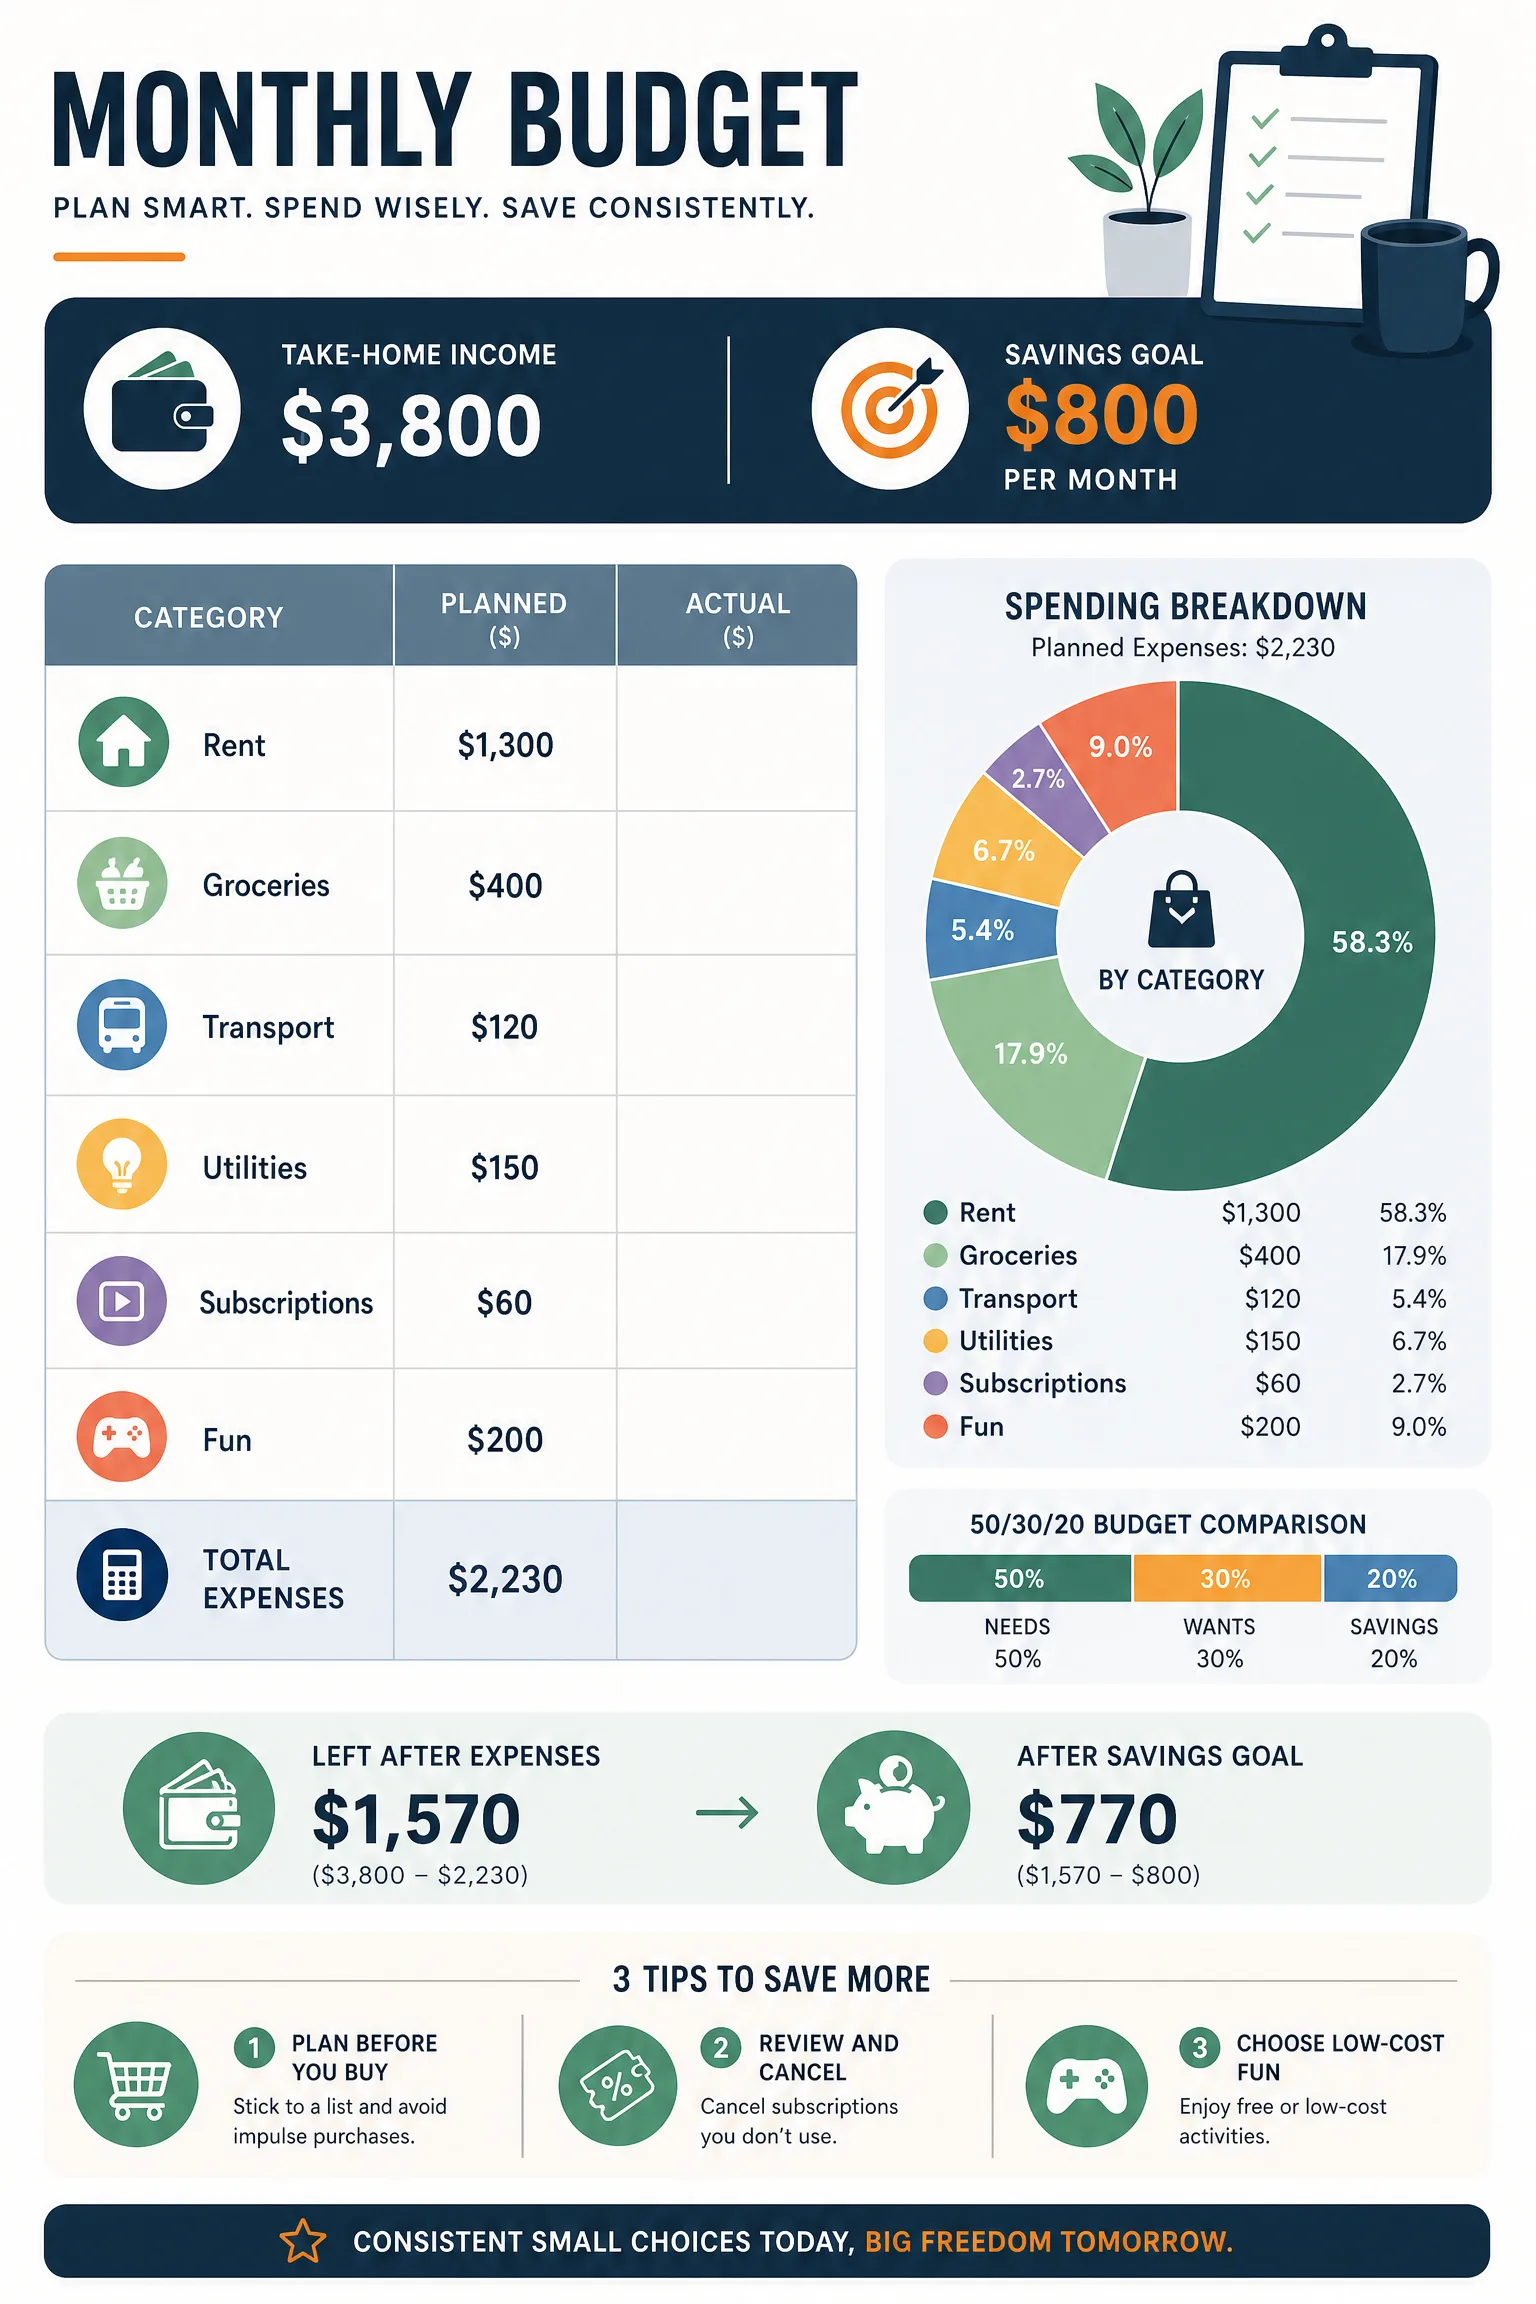
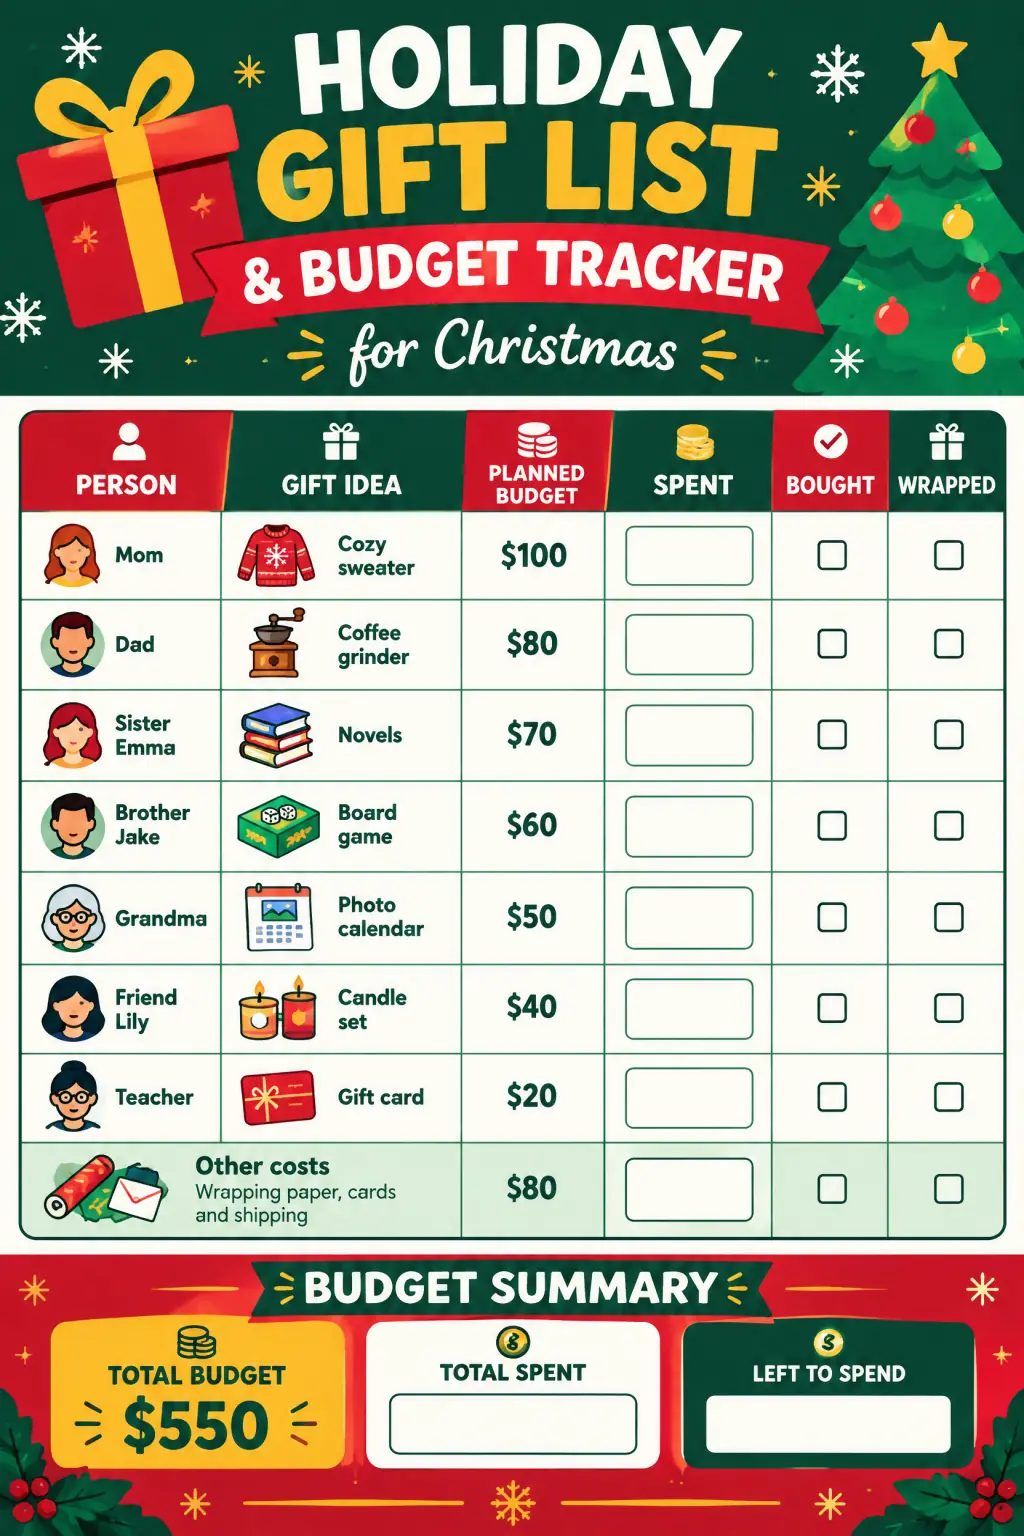
Free printable planners, blank or filled in by AI from your details.
Related Infographics
All Finance & FinTech infographics →Personal Retirement Savings Guide 2026
Retirement guide for 2026: median 55–64 savings near $185K, 401(k) limits at $23,500, 3.7% withdrawal research, and Social Security timing.
Private Equity vs Venture Capital Investment Guide 2026
PE vs VC explained: deal structures, fund sizes, return profiles, portfolio company stages, carried interest, LP composition, and 2026 market trends.
Buy Now Pay Later (BNPL) Statistics 2026
BNPL market data: $576B in global transactions, adoption by age group, default rates, regulatory landscape, and impact on consumer spending behavior.
ESG Investing & Sustainable Finance Trends 2026
ESG assets reached $53T in 2026, 36% of managed money. Fund performance, SFDR and SEC rules, ratings gaps, and investor demographics.